Reading view

There are new articles available, click to refresh the page.

How One Executive Recruitment Firm Is Using M&A to Turn Earnings Into Bitcoin

Bitcoin Magazine
How One Executive Recruitment Firm Is Using M&A to Turn Earnings Into Bitcoin

Connecting Excellence Group (XCE) has signed binding Heads of Terms for its first proposed recruitment acquisition, targeting a specialist UK and U.S. recruitment business that generated £1.79 million in revenue and £431,000 in EBITDA over the last 12 months. The target also holds 8.216 Bitcoin.

The deal has not yet closed and remains subject to further due diligence, funding and a definitive purchase agreement. [Read XCE’s full announcement.]

Beyond the headline, the structure of the deal offers an interesting look at how an operating company can use M&A as part of a broader Bitcoin strategy.

XCE (AQSE: XCE | OTCQB: XCELF) wants to acquire profitable recruitment businesses, retain much of the earnings they generate, and expand the pool of internally generated capital available for growth and Bitcoin.

There is also a notable symmetry between buyer and target. XCE’s existing operating business, Spencer Riley, grew revenue 20.6% over its latest 12-month period. The acquisition target grew revenue 21.5% over the same period.

XCE is not simply looking to add scale. It is attempting to acquire growing, profitable businesses and bring them into a listed group with Bitcoin on its balance sheet.

Acquiring Earnings Power

XCE expects to pay £575,000 in initial cash consideration at completion. Approximately £425,000 would settle amounts owed to the target companies by the vendors and return to the group, resulting in an estimated net cash outflow of roughly £150,000 before transaction costs.

Another £60,000 cash payment is due in 2028, while much of the remaining consideration is deferred and tied to EBITDA performance through fiscal 2029. XCE expects to retain approximately 75% to 85% of the acquired business’s cumulative EBITDA during the earn-out period.

Compare that with the business being acquired: £1.79 million in trailing revenue, £1.27 million in gross profit and £431,000 in EBITDA, with revenue growing 21.5% year over year.

The objective isn’t simply to buy more revenue. XCE is attempting to acquire additional earnings power while preserving as much capital as possible.

If the business continues performing after completion, those earnings become another source of capital available for reinvestment, additional acquisitions and Bitcoin.

That is where M&A starts to become part of the Bitcoin strategy.

Acquiring the Balance Sheet, Too

The model can extend beyond revenue and earnings.

When an acquisition target holds cash reserves, XCE can structure a transaction to acquire that reserve from the seller and then change how that capital is held once it sits inside the group. In practice, that could mean raising capital to acquire £1 million of existing cash reserves and subsequently converting that reserve to Bitcoin.

The result is different from simply raising £1 million and spending it on Bitcoin. XCE is acquiring the operating business around the reserve as well: its revenue, earnings and future cash-generating capacity.

This proposed deal provides a direct example of the same principle, except the target has already made the conversion.

It holds 8.216 BTC.

Under the proposed terms, XCE would purchase that Bitcoin at market value with no premium. The cash paid would be matched by Bitcoin of equivalent value moving onto XCE’s balance sheet.

So the Bitcoin isn’t being acquired for free with the operating business. XCE is effectively exchanging cash for an equivalent amount of Bitcoin while separately acquiring the underlying earnings stream.

If completed, however, the transaction would expand both sides of XCE at once: another growing, profitable operating business and another 8.216 BTC on its balance sheet.

That combination is central to the model. An acquisition can potentially add revenue, EBITDA and balance-sheet assets at the same time.

A Decentralized Acquisition Compounder

How XCE intends to operate the businesses after acquisition is another important part of the strategy.

The company is targeting profitable, owner-managed specialist recruitment businesses, but it does not intend to absorb them into a single centralized operating brand.

Acquired companies retain their existing brands, management teams and operating independence while joining a publicly listed group backed by a Bitcoin balance sheet. That makes XCE’s model closer to a decentralized acquisition compounder.

Rather than attempting to create value primarily through integration and cost cutting, the strategy is designed to let individual businesses continue operating with autonomy while XCE provides permanent ownership, access to the listed group and centralized capital allocation.

XCE’s existing business gives some context for the type of growth it is looking to add. Spencer Riley generated approximately £1.84 million in revenue during the 12 months ended June 30, up 20.6% from the prior year. The proposed acquisition target grew at a similar rate, with revenue rising 21.5%.

If XCE can continue acquiring businesses with similar economics, the group can potentially compound by adding new earnings streams without dismantling the businesses producing them. Those earnings then feed into a common capital allocation framework in which Bitcoin is one potential destination.

Building More Than One Source of Capital

XCE isn’t relying on operating earnings alone to grow its Bitcoin position. The company reported 72.94 BTC as of September 1, up from 9.27 BTC at its December 2025 IPO. Capital markets activity has contributed to that growth.

Most recently, longtime investor Adam Back subscribed for new XCE shares through the transfer of 10 BTC to the company, increasing its Bitcoin holdings by 15.9%.

M&A introduces another source of potential capital alongside those transactions: earnings and balance-sheet assets acquired with the operating businesses themselves.

Put together, the model looks something like this:

Acquire profitable businesses → retain their autonomy and earnings power → grow group cash generation → allocate capital across further acquisitions and Bitcoin → repeat.

External capital can provide immediate purchasing power, as the Adam Back transaction demonstrates. Acquired reserves can add balance-sheet capital. Profitable operating businesses can continue generating capital as long as they perform. XCE is attempting to combine all three.

The Operating Economics Come First

Bitcoin does not make a poor acquisition a good one. XCE still has to acquire quality businesses at sensible prices, preserve their earnings power and allocate the resulting capital effectively. But the strategy illustrates how Bitcoin can fit inside a traditional operating company without becoming disconnected from the business underneath it.

The decentralized structure is important here. XCE does not need every acquired company to become a “Bitcoin business.” The recruitment companies can continue serving their customers, operating under their existing brands and generating earnings. Bitcoin sits at the group level as part of the broader capital allocation strategy.

That creates a different way to think about Bitcoin on a corporate balance sheet.

The company can raise outside capital. It can acquire existing reserves and change how they are held. It can acquire profitable businesses and retain the cash they generate. Management can then allocate capital between operations, additional acquisitions, other corporate needs and Bitcoin. That is how XCE is using M&A to turn earnings into Bitcoin.

Not by automatically converting every pound of profit into BTC, but by building a decentralized group of profitable businesses capable of producing more earnings and making Bitcoin one destination for the capital they generate.

For operators, that may be the more interesting question: not simply how to find more capital to buy Bitcoin, but how to build a business capable of generating more capital in the first place.

Disclaimer: This content was prepared on behalf of Bitcoin For Corporations for informational purposes only. It reflects the author’s own analysis and opinion and should not be relied upon as investment advice. Nothing in this article constitutes an offer, invitation, or solicitation to purchase, sell, or subscribe for any security or financial product.

This post How One Executive Recruitment Firm Is Using M&A to Turn Earnings Into Bitcoin first appeared on Bitcoin Magazine and is written by Nick Ward.
BlackRock Re-Underwrites Bitcoin, and the Portfolio Math Still Holds

Bitcoin Magazine

BlackRock Re-Underwrites Bitcoin, and the Portfolio Math Still Holds

Bitcoin’s roughly 50% decline from its October 2025 high has created a useful test for the institutional investment thesis. It is relatively easy to make the case for a new asset while prices are rising, correlations are favorable and capital is flowing into the market. The more revealing exercise comes after a major drawdown, when investors can revisit the original assumptions and determine which were structural and which were simply products of the preceding cycle.

That is effectively what BlackRock has done in its latest research, Re-Underwriting Bitcoin: Still a Portfolio Diversifier. Rather than treating the recent drawdown as evidence for or against Bitcoin in isolation, the firm returns to the question most relevant to an allocator: how has Bitcoin actually affected the risk and return characteristics of a diversified portfolio?

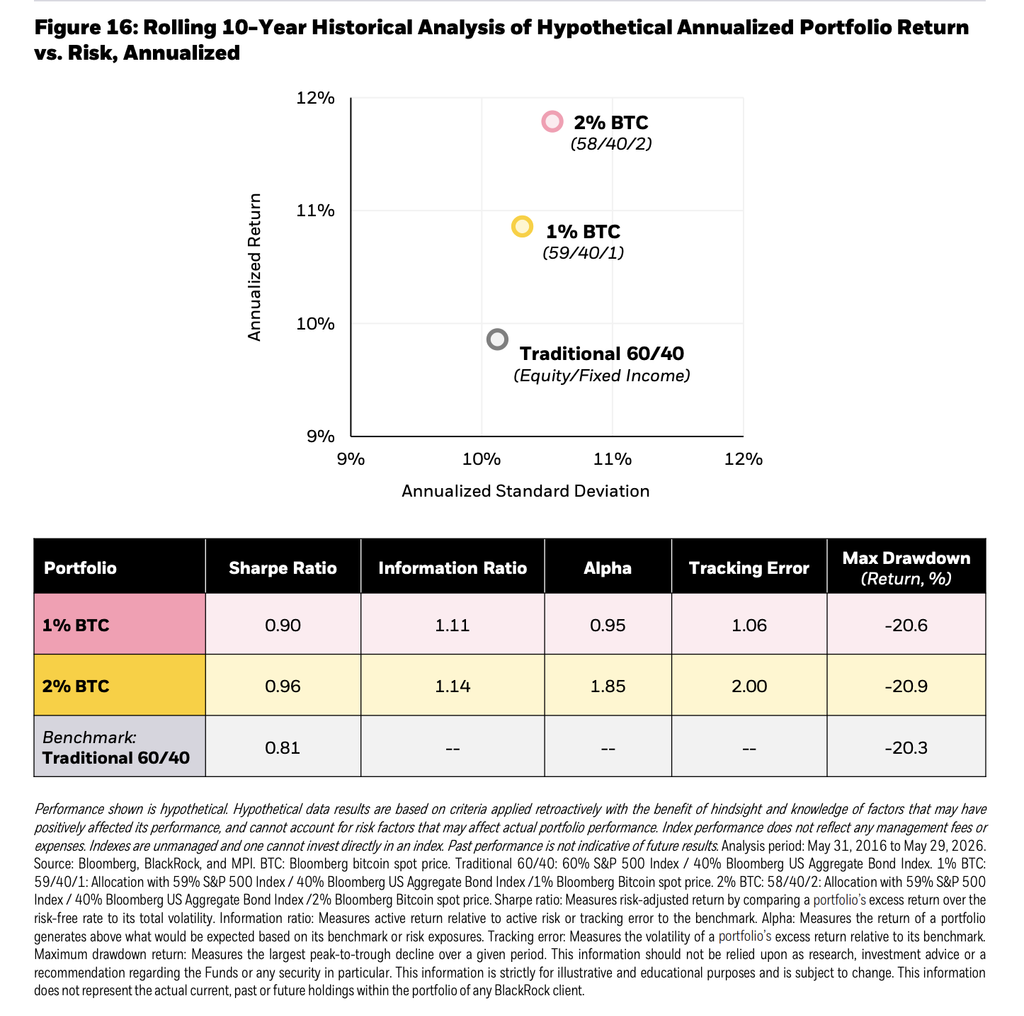
The results are more consequential than the headline return figures suggest. In BlackRock’s rolling 10-year analysis through May 29, 2026, a traditional 60/40 equity and fixed-income portfolio generated an annualized return of approximately 9.9% with annualized standard deviation of roughly 10.1%. Introducing a 1% Bitcoin allocation increased annualized return to approximately 10.9%, while volatility moved only modestly higher to roughly 10.3%. At a 2% allocation, annualized return reached approximately 11.8%, with standard deviation of about 10.6%.

Put differently, the 2% allocation added roughly 190 basis points of annualized return relative to the traditional portfolio while increasing annualized volatility by approximately 50 basis points. The portfolio’s Sharpe ratio improved from 0.81 to 0.96, while maximum drawdown changed from -20.3% to -20.9%. Those figures are hypothetical and backward-looking, but they illustrate why judging Bitcoin primarily by its standalone volatility can produce an incomplete assessment of its portfolio impact.

The more relevant question is how that volatility interacts with everything else an investor already owns. BlackRock continues to characterize Bitcoin as having risk and return drivers that are fundamentally different from traditional assets, rooted in its fixed supply, decentralized structure and independence from any sovereign issuer. Those characteristics do not prevent Bitcoin from trading alongside risk assets during periods of deleveraging, but BlackRock’s research suggests those correlations have historically been episodic rather than permanent.

That distinction helps explain the portfolio results. A modest allocation does not import Bitcoin’s standalone volatility into a portfolio on a one-for-one basis. What matters is the marginal contribution of that allocation to total portfolio risk relative to the return it has historically generated. In BlackRock’s analysis, that trade-off remained favorable at 1% and 2%, even after incorporating one of Bitcoin’s most significant recent drawdowns.

Why 1–2% keeps appearing in BlackRock’s work

This is not the first time BlackRock has arrived at this range. Its earlier portfolio research approached Bitcoin sizing through risk contribution, concluding that a 1–2% allocation could represent a reasonable range for investors willing and able to accept Bitcoin’s risk. At those weights, BlackRock found that Bitcoin could contribute a similar share of overall portfolio risk as an individual mega-cap technology holding in a conventional 60/40 portfolio. Beyond 2%, however, Bitcoin’s contribution to total portfolio risk begins to increase disproportionately.

The new analysis approaches the same question from the opposite direction. Rather than asking how much risk Bitcoin contributes, it examines what investors historically received for assuming that additional risk. The improvement in Sharpe ratio from 0.81 for the traditional portfolio to 0.90 with 1% Bitcoin and 0.96 with 2% Bitcoin suggests that the incremental return historically more than compensated for the additional portfolio-level volatility.

This does not establish 1% or 2% as an optimal allocation, and BlackRock does not present it that way. The appropriate exposure will depend on liquidity requirements, investment horizon, governance constraints and risk tolerance. What the analysis does provide is a more rigorous framework for the discussion. The allocation question can increasingly be evaluated in terms of marginal risk, correlation, drawdown and portfolio efficiency rather than through a binary debate over whether Bitcoin itself is too volatile to own.

BlackRock has also seen the demand firsthand

There is another dimension to BlackRock’s latest analysis that is difficult to separate from the firm’s experience in the market.

BlackRock launched the iShares Bitcoin Trust, IBIT, in January 2024. Less than a year later, it had accumulated more than $50 billion in assets, making it what BlackRock itself has described as the largest exchange-traded product launch in history. It reached that milestone roughly five times faster than the previous record holder.

Its significance has only grown since then. BlackRock now describes IBIT as the world’s largest and most traded Bitcoin ETP, and the fund became the firm’s highest-revenue ETF in 2025 despite competing within a global BlackRock lineup of more than 1,000 products.

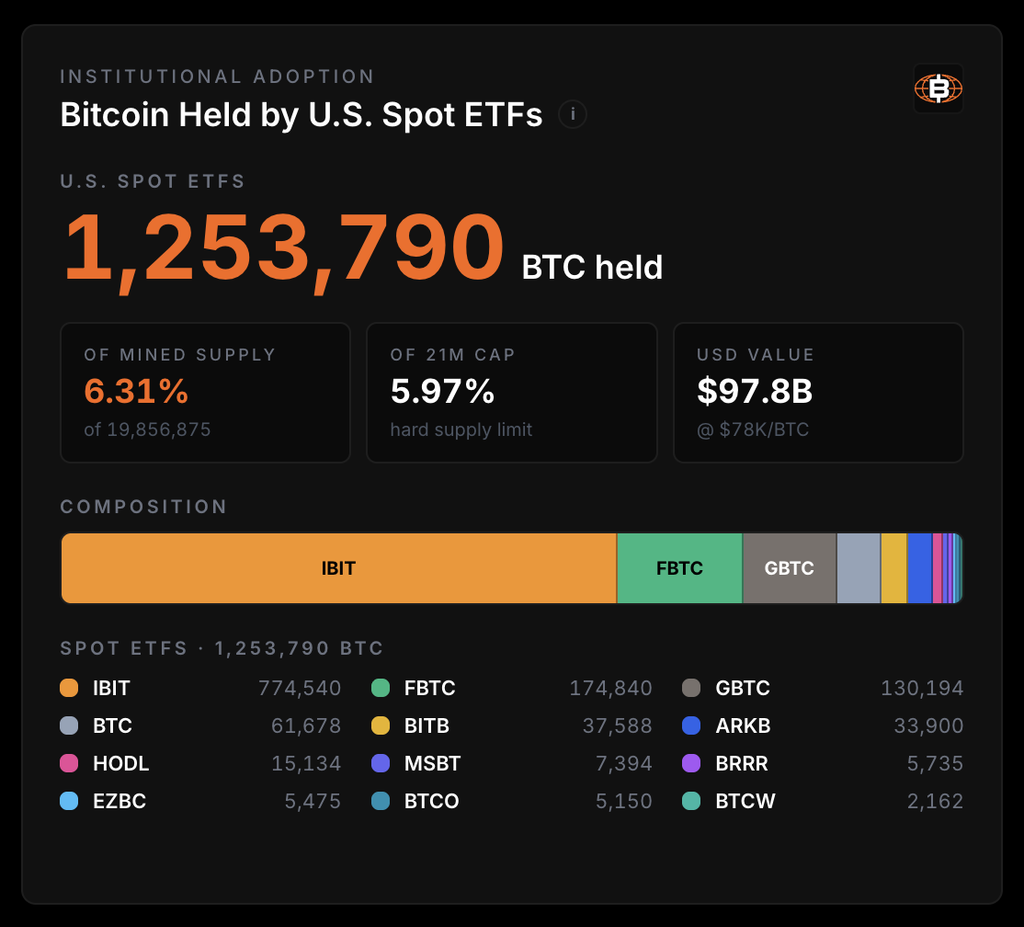
The concentration within the U.S. spot Bitcoin ETF market is equally notable. According to current ETF holdings data tracked by Bitcoin For Corporations, U.S. spot Bitcoin ETFs collectively hold approximately 1.25 million BTC, representing nearly 6% of Bitcoin’s fixed 21 million supply. IBIT alone accounts for roughly 775,000 BTC, or more than 60% of the Bitcoin held across the U.S. spot ETF complex.

View the full Bitcoin ETF Dashboard.

That does not make BlackRock’s research independent of commercial context; IBIT is an important and increasingly valuable BlackRock product. That context should be understood rather than ignored. But it also means the firm’s reassessment is occurring alongside more than two years of observing how investors actually use Bitcoin exposure at scale.

The distinction is useful. The theoretical case for Bitcoin as a portfolio asset is increasingly being accompanied by observable allocation behavior. Investors have now had access to Bitcoin through familiar brokerage, advisory and institutional infrastructure across multiple market regimes, including periods of rapid appreciation and severe drawdowns. IBIT’s growth suggests that demand has persisted well beyond its initial launch window.

A drawdown is precisely when a thesis should be re-underwritten

The timing of BlackRock’s report may ultimately be more informative than the portfolio simulation itself.

Bitcoin is not being reassessed at an all-time high. BlackRock published the analysis after an approximately 50% drawdown from Bitcoin’s October 2025 peak, a period the firm associates with leveraged positioning being unwound, slowing ETP flows and weaker demand from companies accumulating Bitcoin. Its conclusion is that these forces represented a positioning correction rather than a fundamental change in Bitcoin’s investment case.

That is what re-underwriting is supposed to accomplish. An investment thesis should not survive because investors are attached to it; it should survive because its underlying assumptions continue to hold when conditions change.

For Bitcoin, those assumptions extend beyond historical returns. The asset remains scarce by design, globally liquid, independent of a sovereign issuer and structurally different from the liabilities that dominate traditional portfolios. BlackRock argues that concerns around fiscal sustainability, monetary stability and geopolitical risk may therefore become increasingly relevant to Bitcoin’s long-term adoption.

The portfolio evidence does not prove what Bitcoin will return over the next decade, nor does IBIT’s success establish what an appropriate allocation should be. What the two developments show together is that the institutional conversation has advanced considerably. Bitcoin is no longer being evaluated solely as an unconventional asset that institutions may or may not choose to own. It is increasingly being evaluated through the same disciplines applied elsewhere in capital allocation: sizing, risk contribution, correlation, liquidity, drawdown and expected return.

What this means for corporate leaders

For CFOs, boards and corporate operators, that evolution may be the most important takeaway from BlackRock’s work.

The relevant decision is not whether Bitcoin is volatile; that is already known. Nor does a corporate allocation need to resemble the concentrated Bitcoin strategies pursued by companies that have explicitly built their capital structures around the asset. Between zero exposure and a Bitcoin-centric balance sheet sits a much broader spectrum of possible allocations.

BlackRock’s research provides a useful framework for thinking about that spectrum. A relatively small allocation was sufficient to materially alter the historical return characteristics of a conventional portfolio without producing a comparable increase in portfolio-level risk. At 2%, approximately 190 basis points of additional annualized return came with roughly 50 basis points of additional annualized volatility in the period studied. The allocation was small; its effect was not.

For corporate leaders, the implication is less about adopting BlackRock’s specific allocation range than adopting the discipline behind the analysis. Bitcoin can be underwritten like any other strategic allocation: define its purpose, determine an acceptable risk contribution, establish liquidity and governance requirements, size the position accordingly and periodically revisit the assumptions.

That is a considerably more mature question than whether a company should simply “buy Bitcoin.”

As Bitcoin becomes more deeply integrated into institutional portfolios and financial infrastructure, the burden of analysis is shifting. The question facing the C-suite is increasingly not whether Bitcoin belongs in the conversation, but what allocation, if any, can be justified by the company’s objectives, constraints and cost of capital.

BlackRock has now re-underwritten that question after another full market cycle and a roughly 50% drawdown. Its historical portfolio math still makes the case that, in measured amounts, Bitcoin can improve the equation. For corporate decision-makers, that is the takeaway worth bringing into the boardroom.

Disclaimer: This content was prepared on behalf of Bitcoin For Corporations for informational purposes only. It reflects the author’s own analysis and opinion and should not be relied upon as investment advice. Nothing in this article constitutes an offer, invitation, or solicitation to purchase, sell, or subscribe for any security or financial product.

This post BlackRock Re-Underwrites Bitcoin, and the Portfolio Math Still Holds first appeared on Bitcoin Magazine and is written by Nick Ward.
Why Bitcoin Mining and AI Are Merging, Not Colliding

Bitcoin Magazine

Why Bitcoin Mining and AI Are Merging, Not Colliding

If you’ve scanned headlines over the last year, you’ve likely seen the prevailing market narrative: Bitcoin miners are pivoting to AI data centers, signaling a retreat from proof-of-work.

To casual observers, this looks like a surrender, proof that Bitcoin was just a temporary placeholder until a “better” compute workload arrived.

However, through the lens of power infrastructure and energy economics, that narrative gets the reality completely backwards. The migration isn’t a sign of Bitcoin’s weakness; it is a long-overdue, structurally bullish rebalancing of capital efficiency and global energy pricing.

Here is the underlying reality the market misunderstands.

AI vs. Bitcoin: Opposite Workloads, Same Megawatts

The misconception stems from assuming all digital workloads are created equal. In reality, Artificial Intelligence and Bitcoin Mining require completely opposite operational environments:

  • AI Training Clusters Are Fragile: If a 100-megawatt AI facility drops power mid-run, millions of dollars of LLM training state are destroyed. AI demands high-grade baseload power, ultra-low latency fiber, and 99.999% continuous uptime.
  • Bitcoin Miners Are Ultra-Flexible: Bitcoin mining is completely indifferent to latency or location. ASICs can operate anywhere power is cheap. Crucially, if grid power prices spike or local utilities demand load reduction, a miner can curtail power in seconds without losing data or damaging hardware.

The Power Bottleneck: Why Energized Sites Are the Ultimate Asset

AI hyperscalers face a massive speed-to-market bottleneck: securing new 100+ megawatt grid interconnections with utilities can take 3 to 5 years. Meanwhile, Bitcoin miners spent the last decade securing high-voltage interconnections, power purchase agreements (PPAs), and physical site footprint.

Rather than AI “pricing miners off the grid,” miners are acting as pragmatic energy arbitrageurs. They don’t care about the compute payload, they care about maximizing dollar yield per megawatt.

When post-halving mining margins tighten, leasing or retrofitting prime grid-tied sites for high-margin AI workloads becomes a natural capital allocation play. Miners aren’t being evicted; they are monetizing their most valuable asset: time-to-power.

Taming Balance Sheet Volatility

The primary structural weakness of public Bitcoin mining companies has always been balance sheet exposure during bear markets. When hash prices drop, debt-heavy miners are forced to dump mined Bitcoin reserves onto the open market to pay electricity bills and corporate overhead—creating downward price pressure.

The AI shift fundamentally alters this balance sheet dynamic:

  1. Predictable USD Cash Flow: Multi-year hosting leases signed with AI hyperscalers generate steady, high-margin dollar revenue.
  2. Reduced Forced Selling: With corporate overhead covered by AI revenue, operators no longer need to dump their Bitcoin treasury at market bottoms.
  3. The “Mullet” Data Center: Forward-thinking operators run a hybrid model, using high-margin AI workloads on grid-tied power to cover fixed costs, while using flexible Bitcoin mining to monetize off-peak power and provide lucrative demand-response services back to the grid.

The Bottom Line: Pure Energy Capitalism

The shift taking place across global data centers isn’t a trade-off where one technology “wins” and the other loses. It is a market optimization.

AI hyperscalers get the energized, grid-connected real estate they need to meet immediate compute demands without waiting half a decade in a utility queue. Bitcoin miners get predictable cash flows, lower cost of capital, and stronger balance sheets to navigate halving cycles.

Instead of competing for power, AI and Bitcoin infrastructure are converging into a symbiotic relationship, allocating every megawatt of global energy to its highest and best financial use.

Disclaimer: This content was prepared on behalf of Bitcoin For Corporations for informational purposes only. It reflects the author’s own analysis and opinion and should not be relied upon as investment advice. Nothing in this article constitutes an offer, invitation, or solicitation to purchase, sell, or subscribe for any security or financial product.

This post Why Bitcoin Mining and AI Are Merging, Not Colliding first appeared on Bitcoin Magazine and is written by Nick Ward.
Bitcoin ETFs Add Nearly $800 Million in the Wake of Coldcard Exploit

Bitcoin Magazine

Bitcoin ETFs Add Nearly $800 Million in the Wake of Coldcard Exploit

One of the biggest Bitcoin security stories of the year unfolded last week as a firmware exploit affecting certain Coldcard hardware wallets renewed industry debate around self-custody and operational security.

At the same time, another story was developing in the background.

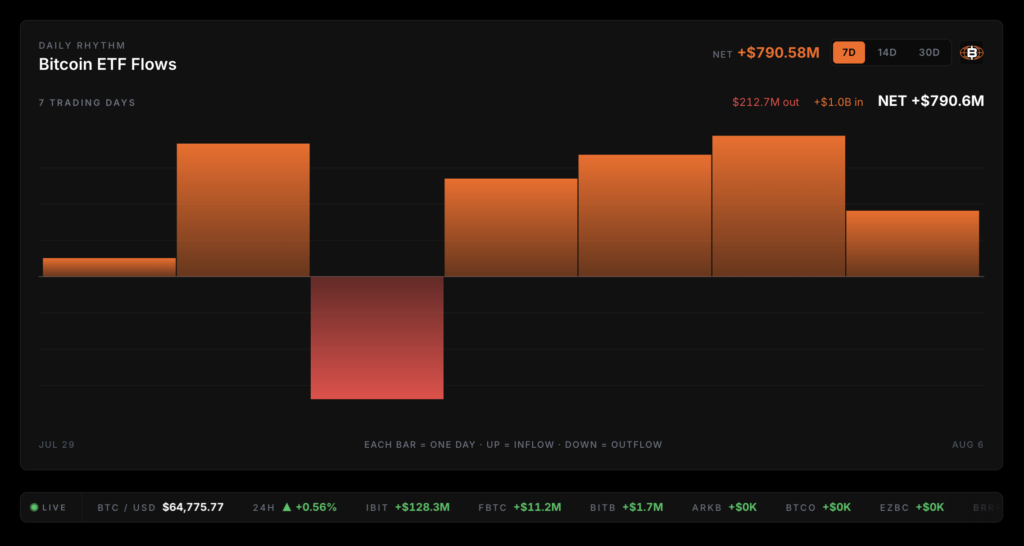
Over the same seven trading days, U.S. spot Bitcoin ETFs attracted $790.6 million in net inflows, according to the Bitcoin For Corporations ETF Dashboard. More than $1.0 billion entered the funds while $212.7 million exited, resulting in one of the strongest weekly periods in recent months.

The two developments are not necessarily related. ETF flow data cannot tell us why investors bought Bitcoin. What it does tell us is what they actually did. And during a week dominated by security headlines, institutional capital continued flowing into regulated Bitcoin investment products.

One Red Day Didn’t Change the Trend

The seven-day flow chart tells a simple story. There was one notable setback.

On July 31, U.S. spot Bitcoin ETFs recorded $212.7 million in net outflows, the only negative session during the period.

After that, buyers returned almost immediately.

The next four trading sessions posted consecutive gains:

  • Aug. 3: +$170.1M
  • Aug. 4: +$207.8M
  • Aug. 5: +$241.6M
  • Aug. 6: +$99.4M

By the end of the week, the positive days had more than offset the lone selloff.

Instead of focusing on individual trading sessions, the seven-day view shows where capital ultimately moved—and during this period, it moved into Bitcoin.

BlackRock Continued to Lead the Way

As has been the case for much of the ETF era, BlackRock’s IBIT accounted for the majority of inflows.

Over the seven-day period:

  • IBIT attracted $757.5 million in rolling net inflows.
  • It extended its streak to four consecutive inflow days.
  • On the latest trading day alone, it added $128.3 million.

Other issuers also participated.

Fidelity’s FBTC added $11.2 million on the latest session, while Bitwise’s BITB added $1.7 million. A handful of funds experienced modest outflows, but none came close to offsetting IBIT’s continued strength.

The result was a week where inflows remained broad enough to keep total ETF demand firmly positive.

What ETF Flows Can and Can’t Tell Us

ETF flows are one of the clearest windows into institutional participation in Bitcoin. They show where money moved. They do not explain investor motivation.

It’s impossible to conclude from one week’s data whether buyers viewed the Coldcard exploit as insignificant, saw it as an opportunity to buy, or simply continued executing long-term allocation strategies that were already in motion.

What can be observed is that institutional demand remained resilient during a week when Bitcoin security dominated industry headlines.

A security incident involving one custody solution is different from the broader investment case for Bitcoin, and ETF investors appeared comfortable continuing to allocate capital through regulated products.

Why This Matters

Bitcoin is no longer accessed through a single path. Some investors choose self-custody. Others hold Bitcoin through public companies. Many institutions access Bitcoin through regulated ETFs. Each approach comes with its own tradeoffs, operational considerations, and risk profile.

Events like the Coldcard exploit naturally increase attention on custody practices. At the same time, ETF flow data provides a useful lens into whether institutional demand is changing beneath the headlines.

This week, the numbers suggest demand remained intact.

Follow Institutional Bitcoin Demand in Real Time

Daily ETF flows have become one of the most important indicators of institutional participation in Bitcoin.

The spot Bitcoin ETF Dashboard tracks:

  • Daily net inflows and outflows
  • Rolling 7-day momentum
  • Issuer-by-issuer rankings
  • Estimated Bitcoin held by U.S. spot ETFs
  • Market share and concentration trends
  • Historical flow data across every issuer

Whether you’re monitoring institutional adoption, evaluating market structure, or simply trying to separate headlines from capital flows, the dashboard provides a real-time view of where money is moving.

Explore the live Bitcoin ETF Dashboard: https://bitcoinforcorporations.com/bitcoin-etf-dashboard/

As new flow data is published each trading day, the dashboard updates to help investors and corporate decision-makers track one of the market’s clearest signals of institutional Bitcoin demand.

Disclaimer: This content was prepared on behalf of Bitcoin For Corporations for informational purposes only. It reflects the author’s own analysis and opinion and should not be relied upon as investment advice. Nothing in this article constitutes an offer, invitation, or solicitation to purchase, sell, or subscribe for any security or financial product.

This post Bitcoin ETFs Add Nearly $800 Million in the Wake of Coldcard Exploit first appeared on Bitcoin Magazine and is written by Nick Ward.
❌