Reading view

There are new articles available, click to refresh the page.

DAO vs Foundation vs Company: Three Ways to Run the Same Thing

A nonprofit once handed back roughly $500 million and dissolved itself on purpose. Here is what that taught crypto about legal structure, onchain governance and who actually holds power.

Dark branded Sky Ecosystem graphic titled DAO vs Foundation vs Company, with three columns showing that a DAO holds authority, a foundation holds legal capacity and a company holds execution.
Three structures, three different jobs. Only one of them can sign a contract.

In May 2021, a nonprofit gave away 84,000 governance tokens. At the time they were worth close to $500 million.

Then it shut itself down. On purpose.

That nonprofit was the Maker Foundation. The protocol it had been stewarding is known today as Sky Protocol.

And that single decision still frames a question every onchain project eventually has to answer out loud.

Who actually runs this thing?

There are three answers in circulation. A DAO. A foundation. A company. Most people treat them as competing options.

They are not. They are layers. And the protocols that hold up under pressure tend to use all three.

DAO vs Foundation vs Company: What Actually Separates Them

Short version first.

  • A DAO is a decision-making system. Token holders vote, code executes. No registered office, no signature on a lease.
  • A foundation is a legal entity with no owners. It can hold IP, sign contracts, publish reports and instruct a law firm. It is not supposed to control the protocol.
  • A company is a legal entity with owners. Fast, familiar, easy to hire through. It also has a boss, which is exactly the problem.

The real dividing line is not ideology. It is far more boring than that.

Who can a court sue. Who can open an account. Who signs when a vendor asks for a signature.

A DAO, on its own, cannot sign anything. That gap is the entire story.
Comparison chart of DAO, foundation and company across seven capabilities including signing contracts, opening a bank account, shielding members from personal liability and setting protocol risk parameters.
Signing power, liability shield and control, side by side. The gaps are the reason legal wrappers exist.

Why a Pure DAO Leaves Token Holders Legally Exposed

Here is the part most “what is a DAO” explainers skip.

If a group acts together for profit without registering an entity, most legal systems already have a default box waiting: general partnership, or unincorporated association.

In a general partnership, members are personally liable for the group’s debts.

That is not hypothetical anymore.

In CFTC v. Ooki DAO, a federal court in California accepted that a DAO could be sued in its own name as an unincorporated association made up of its token holders.

The regulator’s position was blunt: vote your governance tokens, and you are a member.

Members of a for-profit unincorporated association can be personally liable under partnership principles.

An earlier case, Sarcuni v. bZx DAO, noted that governance token holders could be treated as members of a general partnership under California law.

Read that twice if you hold governance tokens and vote with them.

This is why “we are just a DAO, we have no entity” stopped being a flex around 2023. Governance is not a shield. Governance without a legal wrapper is exposure.

The Crypto Foundation Structure Is a Legal Wrapper, Not a Boss

Foundations exist to absorb that exposure without becoming a boss. Three shapes dominate.

  • Cayman foundation company. Ownerless. Run by a small board or council, with token holders named as beneficiaries. Common for large token ecosystems holding IP and contracts.
  • Swiss foundation. Strong reputation, better banking access, higher running costs.
  • Wyoming DUNA. A US nonprofit association purpose-built for DAOs, effective July 1, 2024. No mandatory board. Bylaws can point directly at onchain votes. Members are shielded from the association’s debts.

The catch is honest and worth saying out loud. A foundation fixes the paperwork problem by creating a small group of humans who hold a pen. That is a genuine centralization cost.

Which is why wording matters. The footer of skyeco.com reads:

“This website is managed by Sky Frontier Foundation (SFF). The SFF is an independent entity and does not have authority over Sky Protocol, its smart contracts, or governance decisions.”

That is a foundation publicly disclaiming control over the thing it supports. Not modesty. Architecture.

The Company Model Buys Speed and Cannot Shed Control

Companies are still everywhere in crypto, for good reason. You can hire. You can sign an engagement letter. You can buy insurance.

What you cannot do is make the control disappear.

Regulators have not drawn a neat line between “the DAO” and “the dev shop.”

In token enforcement actions, legal analysts note that agencies have named any company involved with the token, development companies included.

If your company holds admin keys, your decentralization story is a marketing asset, not a legal defense.

So the pattern that actually emerged is not DAO or foundation or company. It is:

  • DAO for authority
  • Foundation for legal capacity
  • Independent companies for execution

Three layers, deliberately kept apart.

Diagram of the Sky Ecosystem governance stack showing Sky Governance holding authority, Sky Frontier Foundation holding legal capacity and the Sky Agent Network handling execution.
Authority, legal capacity and execution, kept in separate hands.

How Sky Ecosystem Splits Authority, Publishing and Execution

Sky Ecosystem is a clean worked example, because each layer is named differently on purpose.

  • Sky Governance holds authority. Staked SKY activates voting power over risk parameters, collateral types, debt ceilings and protocol upgrades. Proposals move through forum review, then onchain voting, then execution. Once executed, a change cannot be reversed directly. It can only be challenged by passing a new proposal.
  • Sky Frontier Foundation publishes. Reports, disclosures, formal positions. It does not set parameters.
  • Sky Agents execute. Spark, Grove, Obex, Osero and others are independent capital allocators. They access USDS liquidity under governance-set risk parameters and deploy it. They are not subsidiaries.

The naming discipline is not pedantry. It is the difference between “Sky Governance voted to change the rate” and “the foundation changed the rate.” Only one of those is true, and only one survives a regulator reading it.

Scale check. Sky Protocol currently shows roughly $14.15B in Total Collateral backing about $11.48B in stablecoin supply.

Across the wider landscape, DeepDAO data put all DAO onchain treasuries above $26B combined in Q1 2026. This is not a governance thought experiment.

Where the Sky Savings Rate, sUSDS and USDS Fit In

Structure feels abstract until it touches yield. Here is exactly where it does.

  • USDS is the base stablecoin. Independent allocators draw it against governance-approved collateral.
  • Sky Agents deploy that liquidity into diversified strategies and pay for the access.
  • Those payments accrue as protocol revenue.
  • The Sky Savings Rate is funded from it. Variable, and set by Sky Governance rather than a pricing committee.
  • sUSDS is how you hold it. Supply USDS, receive sUSDS, and the position accrues automatically. No lockups, no fees to exit.
So the governance question is a yield question.

If you hold sUSDS, the rate you receive is the output of a public process with a public record of who decided what and when.

You can read the forum thread. You can read the executed spell. You can check the dashboard.

Compare that to a rate that changed because an unnamed committee met on a Tuesday.

Flow diagram showing USDS drawn against approved collateral, deployed by Sky Agents, accruing protocol revenue, funding the governance-set Sky Savings Rate and accruing to sUSDS holders, with 14.15 billion dollars in total collateral and 11.48 billion in stablecoin supply.
From a governance vote to the rate accruing in sUSDS, with the current collateral and supply figures.

The 2026 Shift: DAO Legal Structures Are Coming Onshore

Two things moved the conversation recently.

First, the Uniswap Foundation proposed moving Uniswap Governance into a Wyoming DUNA, named DUNI. If adopted it becomes the largest DAO using the statute.

A coalition of crypto organizations then wrote to the US Treasury asking for federal recognition of the DUNA model.

Second, credit agencies started grading governance. When S&P Global assigned Sky Protocol a B- issuer credit rating, the first ever given to a DeFi protocol, it flagged governance concentration and low voter participation as risk factors. Not code quality. Governance.

That is the real trend. Governance design is now a credit input.

And the numbers deserve honesty. Most DAO proposals draw participation in the 5% to 15% range.

An OpenZeppelin governance review found that in 17 of 23 major DAOs, the top 10 delegates held enough voting power to pass a proposal on their own.

Decentralization on paper is not decentralization in practice.

Bar chart showing typical DAO proposal turnout at 5 to 15 percent, 17 of 23 major DAOs where the top 10 delegates can pass a proposal alone, and DAO treasuries holding 60 to 90 percent of value in their own governance token.
Decentralization on paper versus decentralization in practice.

So Which Structure Should a Protocol Actually Pick?

A rough decision frame.

  • Public infrastructure with a global contributor base? Foundation plus DAO.
  • Distributing revenue to holders? A nonprofit DUNA will not fit. Look at LLC structures.
  • Pre-launch with a small team shipping fast? A company, plus a credible plan to reduce control.
  • Already decentralized and worried about member liability? A DUNA or an offshore foundation, and stop delaying.

The one answer that is clearly wrong is doing nothing and hoping the word “decentralized” holds up in court. Ooki settled that argument.

Timeline from 2018 to 2026 marking the Maker Foundation formation, the MKR contract handover, the 2021 dissolution, the Wyoming DUNA taking effect, the Sky Ecosystem upgrade, the first S and P credit rating for a DeFi protocol and DAOs moving legal wrappers onshore.
Eight years of protocols answering the same structural question.

The Question Nobody Has a Clean Answer To

Here is what I keep circling back to.

The Maker Foundation dissolved itself in 2021. Sky Frontier Foundation exists today and openly disclaims authority over the protocol.

Both were the right call at the time, which suggests these structures are not permanent identities at all. They are stages.

So, a question worth arguing about below.

If a foundation’s job is to eventually make itself unnecessary, how do you tell the difference between one genuinely winding down its influence and one quietly becoming the boss?

I have a view. I would rather hear yours first.


DAO vs Foundation vs Company: Three Ways to Run the Same Thing was originally published in Coinmonks on Medium, where people are continuing the conversation by highlighting and responding to this story.
Tokenization Is No Longer Just About Crypto: Wall Street Is Building New Financial Rails on…

Tokenization Is No Longer Just About Crypto: Wall Street Is Building New Financial Rails on Blockchain

Photo by Robb Miller on Unsplash

For years, blockchain has occupied the public imagination as a technology synonymous with cryptocurrency. Bitcoin, altcoins, decentralized finance, NFTs, and various experiments with digital assets became its most visible manifestations.

But developments in financial markets over the past few years point in a rather different direction.

Some of the assets seeing increasing on-chain activity now come from the most conventional corners of finance: U.S. Treasuries, money market funds, gold, and even equities. A report by CoinShares and Token Terminal published in August 2026 suggests that this development no longer stops at issuing digital representations of existing assets. Tokenized real-world assets are increasingly being used across lending, trading, derivatives, and collateral.

This changes the question surrounding tokenization.

The question is no longer simply, what assets can be put on a blockchain?

The more interesting question is:

what happens when traditional financial instruments begin using blockchain as part of their infrastructure?

From Crypto-Native Assets to Real-World Assets

Illustration created using Copilot 365 (Author)

One number captures this shift particularly well.

RWA deposits across lending platforms and decentralized exchanges reached approximately US$7.4 billion in the second quarter of 2026, more than tripling from around US$2.3 billion a year earlier. The movement becomes even more notable because it occurred while total DeFi deposits declined by approximately 15%. The contrast was even sharper in spot markets: crypto-native spot activity on decentralized exchanges fell by around 70%, while spot trading in tokenized RWAs increased by approximately 220%.

The US$7.4 billion figure, however, does not represent the entire RWA market. It measures assets deposited and used across lending platforms and decentralized exchanges. CoinShares had previously estimated the broader market capitalization of on-chain tokenized RWAs at more than US$40 billion, encompassing tokenized funds, equities, and commodities.

The distinction between these two measures matters.

Tokenization can grow first through issuance, but the next measure is usage. An asset can be issued on-chain without subsequently becoming an active part of financial activity taking place there.

Recent data suggest that this second stage is beginning to emerge.

Tokenized Treasuries and multi-strategy funds have become important components of RWA deposits, while tokenized gold, including PAXG and XAUT, contributes substantially to RWA spot trading activity. In other words, some of the activity developing on blockchain now revolves around instruments whose economic value originates in financial markets outside the blockchain itself.

Tokenization is entering a different phase.

Tokenization Is About More Than Creating Tokens

In its simplest form, tokenization sounds relatively straightforward: a claim on an asset is represented through a digital token.

But representation is only the first layer.

A more consequential change occurs when that digital representation can be transferred, settled, used as collateral, or incorporated into other financial activities through blockchain infrastructure.

Money market funds offer a particularly interesting example because the underlying assets themselves do not necessarily change. Their portfolios can continue to hold conventional money market instruments. What changes is how ownership of those instruments can be represented and used.

BlackRock provides a particularly clear illustration of this architecture.

BlackRock: When Tokenization Does Not Replace the Fund

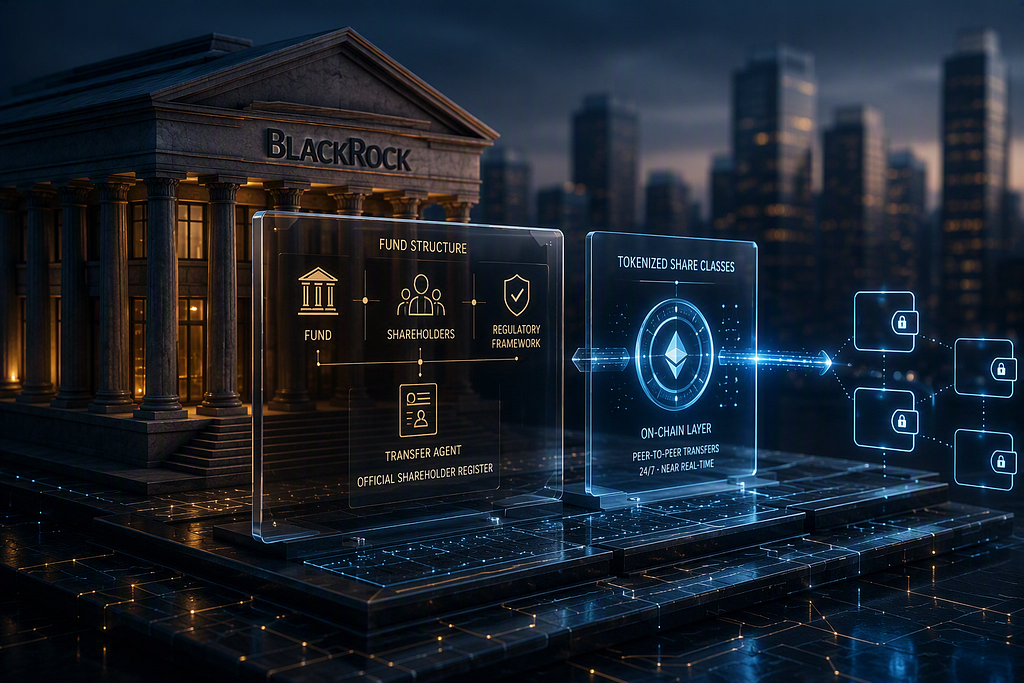
Illustration created using Copilot 365 (Author)

On August 4, 2026, BlackRock launched tokenized on-chain share classes for several money market funds within its European Institutional Cash Series (ICS). Twelve share classes across six funds denominated in sterling, euros, and U.S. dollars received tokenized functionality through J.P. Morgan’s Kinexys infrastructure, with the tokens issued on Ethereum.

This is where the US$311 billion figure needs to be read carefully.

BlackRock said the tokenized functionality was being extended across a money market fund platform with approximately US$311 billion in combined assets under management across 15 markets. This does not mean that US$311 billion in assets were moved onto blockchain all at once. The value actually represented by the tokenized share classes is not equivalent to the total AUM of the broader platform.

The structure of the product is more interesting than the headline figure.

A token represents a share in the underlying ICS fund. The official shareholder register continues to be maintained through transfer-agent infrastructure, while smart contracts allow ownership to move between approved investor wallets. Investors gain 24/7 peer-to-peer transfer capabilities and near-real-time visibility without abandoning the existing fund structure.

In other words, BlackRock is not turning a money market fund into a crypto product.

It is adding blockchain rails to an existing financial product.

The distinction may sound subtle, but conceptually it is significant.

Tokenization here does not replace the existing financial architecture. The fund structure, transfer agent, regulatory framework, and institutional risk management remain in place. Blockchain is added as a new layer for ownership and transfer. BlackRock itself has pointed to potential applications across corporate treasury management, liquidity optimization, digital collateral management, and integration with the wider tokenized financial ecosystem.

This may be a more realistic picture of how blockchain enters institutional finance: not by dismantling the old infrastructure, but through selective integration with infrastructure that institutions already trust.

Franklin Templeton: When Tokenized Assets Start to Work

If BlackRock illustrates how a traditional fund can acquire on-chain transferability, Franklin Templeton demonstrates the next stage: asset utility.

The Franklin OnChain U.S. Government Money Fund is a money market fund whose shares are represented by BENJI tokens through the Benji platform. One BENJI represents one share in the fund, while the platform enables capabilities such as peer-to-peer transfers and blockchain-based ownership records.

In February 2026, Franklin Templeton and Binance took the structure a step further.

Eligible institutional clients were able to use tokenized money market fund shares issued through Benji as off-exchange collateral for trading activity on Binance. The underlying assets remain in regulated custody through Ceffu, while their value is reflected within Binance’s trading environment for collateral purposes.

The functional shift is significant.

An asset that primarily served as an investment can now continue generating yield while simultaneously supporting another activity as collateral. Institutions do not need to move the underlying assets onto the exchange to obtain that functionality. Franklin Templeton describes the arrangement as a way to preserve regulated custody and yield while reducing exposure to exchange counterparty risk.

At this point, tokenization begins to mean something more than digitizing ownership.

The asset starts becoming a programmable financial building block.

And this is where the thesis around RWA rails becomes much more interesting.

From Representation to Financial Plumbing

Put them into the same picture and a fairly clear progression emerges.

The first stage is representation.

Traditional financial instruments acquire digital representations that can be recorded through blockchain infrastructure.

The second is transferability.

Those representations can move between eligible wallets without changing the underlying financial product.

The third is utility.

The tokenized asset can begin functioning as collateral, a yield-bearing asset, or a component of other financial activities. The growth in RWA deposits and trading documented by CoinShares suggests that these uses are no longer merely conceptual designs.

This is why RWA rails may ultimately be a more useful concept than simply RWA tokens.

The token is the instrument. The rails are the infrastructure that allows the instrument to move and be used.

Settlement, custody, transfer agents, wallets, smart contracts, collateral management, trading venues, and regulatory wrappers eventually become parts of the same problem.

What is being built is not simply a tokenized Treasury, tokenized gold, or a tokenized fund.

What is being built is a set of rails through which different forms of assets can interact within a blockchain-based financial environment.

Wall Street Is Not Becoming Crypto

There is a temptation to interpret the involvement of BlackRock, J.P. Morgan, Franklin Templeton, and other large financial institutions as evidence that traditional finance is finally:

“moving into crypto.”

I think that interpretation is too simplistic.

What is emerging instead is a hybrid architecture.

In BlackRock’s case, blockchain supports tokenized share classes, while the official record of ownership remains within transfer-agent infrastructure. Under the Franklin Templeton and Binance arrangement, tokenized collateral can support digital-asset trading while the underlying assets remain in regulated off-exchange custody.

The boundary between on-chain and off-chain, therefore, is not disappearing.

The two are beginning to connect.

CoinShares uses a useful term for this development: Hybrid Finance. Its thesis is not that traditional finance will disappear because of blockchain, but that financial infrastructure is beginning to be rewired through the convergence of blockchain, decentralized financial venues, and tokenized representations of traditional assets.

That is what makes the current phase of tokenization different from the earlier wave of digital assets.

The old question was whether blockchain could create entirely new types of assets.

The question now is shifting:

Can blockchain become part of the infrastructure used to move the assets that already form the foundation of the financial system?

The Rails Are Starting to Show

The scale remains small relative to the global financial system.

CoinShares noted that only around US$2.2 billion of a global equity market worth more than US$100 trillion had been tokenized when its 2026 report was published. It is therefore far too early to suggest that tokenization is replacing existing capital-market infrastructure.

But scale may not be the most important signal at this stage.

The more revealing signal is the change in how tokenized assets are being used.

Over the past year, the development has moved beyond issuance toward lending, trading, collateral, treasury management, and settlement infrastructure. Emerging forms of institutional adoption also do not require institutions to abandon fund structures, regulated custody, transfer agents, or the legal frameworks underpinning traditional finance.

Blockchain is gradually being positioned between these components.

If this development continues, the most important part of the tokenization revolution may ultimately not be the token itself.

The part becoming increasingly invisible may matter most: the rails underneath it.

And like many forms of financial infrastructure, the clearest sign of success may eventually be that people stop noticing the rails are there.

Are we witnessing a gradual evolution of the existing financial system, or the beginning of a fundamentally different market structure?


Tokenization Is No Longer Just About Crypto: Wall Street Is Building New Financial Rails on… was originally published in Coinmonks on Medium, where people are continuing the conversation by highlighting and responding to this story.
❌